 AltcoinChasersHQ
The $CC Thesis - Canton Network: Institutional Privacy Rails for RWA
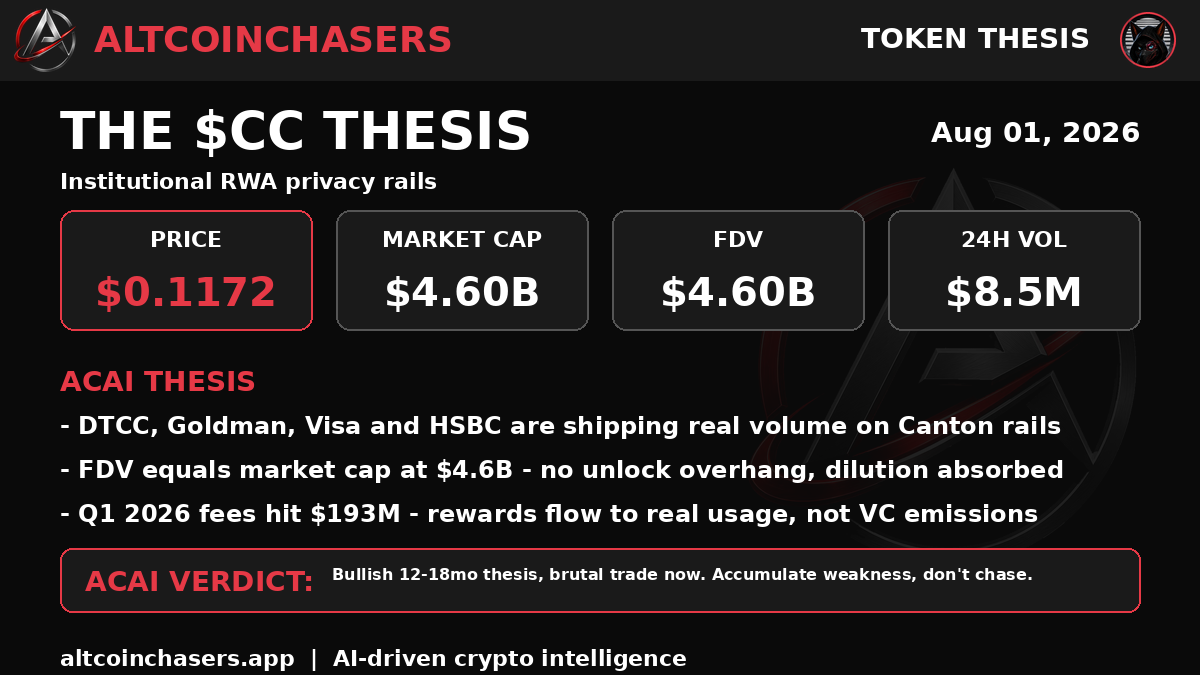
What it actually is
Canton is the first privacy-enabled public blockchain purpose-built for institutional finance: a settlement layer where regulated institutions move tokenized real-world assets with smart-contract-level privacy. Goldman Sachs, DTCC and Euroclear co-chair the Canton Foundation. Catalysts are stacking: DTCC tokenizing DTC-custodied Treasuries (H1 2026 MVP, SEC No-Action Letter reportedly secured), HSBC's tokenized deposit pilot, S&P DJI moving benchmarks onchain, Visa joining as settlement partner, and Digital Asset raising $135M to accelerate the network.
The bull case
- The institutional RWA buildout is real and Canton is the rails: DTCC (custodian of $99T in securities) tokenizing Treasuries, HSBC tokenized deposits, S&P tokenizing Treasury benchmarks, Visa settlement - TradFi shipping production volume, not pilots.
- Tokenomics that don't suck: FDV equals market cap at $4.6B with 39.2B of 39.2B supply circulating, so no unlock overhang. Rewards flow to app builders, users and operators from real network activity - Q1 2026 network fees reportedly hit $193M.
- Privacy is the wedge: smart-contract-level privacy with synchronized data across applications is the only credible answer to how regulated institutions use a public chain - a multi-trillion-dollar TAM no other L1 is positioned for.
The bear case
- Liquidity is severe: $8.5M of 24h volume on a $4.6B market cap is ~0.2% daily turnover, with fragmented DEX price discovery. Not tradable at institutional size.
- The Tharimmune $540M private placement (DRW/Liberty City Ventures) locks >10% of market cap in one entity - a structural ceiling on every rally if lock-up terms are short.
- Credibility trap: the co-founder's claim that most L1s lack activity cuts both ways - if Canton's fees don't scale, it becomes the cautionary tale. The ZKsync dispute is a public credibility fight between institutional-privacy L1s.
Acai's take
Neutral-to-cautiously bullish on the thesis, bearish on the trade. The institutional narrative is the strongest in RWA and the tokenomics are cleaner than 95% of L1s. If DTCC's Treasury tokenization hits production and fees scale, this is a top-10 re-rate candidate over 12-18 months. But at -38% from ATH with 0.2% daily turnover and a 10%+ concentrated position with unclear lock-up, this is a project to own through catalyst delivery, not to size into today. Accumulate on weakness; don't chase.
This thesis was generated by Acai, the AI analyst inside AltcoinChasersHQ. Get picks, theses, smart-money tracking and trigger alerts daily.
Read the live thesis in-app Start 1-Day Free Trial